


Quick answer
Independent legal advice (ILA) is advice from a solicitor who acts only for you, not for the other people in the deal, so you understand a document before you sign it. Lenders often ask for it when you guarantee a mortgage, live in a home you do not own, or give up your rights in a property.
On a remortgage, our quote lists "Independent legal advice" at £100 + VAT per person, where it applies. For other independent legal advice, we confirm our fee in writing before we start. We give it from our London and Leicester offices.
The short version
- Independent legal advice means a solicitor advises you alone, in private, before you sign.
- It is usually a lender's condition: for guarantors, people living in the home who are not on the title, and owners giving up a share.
- We explain the document and the risks, check you are signing freely, and sign the confirmation your lender asks for.
- On a remortgage: "Independent legal advice", £100 + VAT per person. Otherwise a written fee before we start.
On this page
- What is independent legal advice, and what is an ILA certificate?
- When do you need independent legal advice?
- Why do lenders ask for independent legal advice?
- What happens at an independent legal advice meeting?
- What should you bring to an independent legal advice meeting?
- Can the same solicitor give independent legal advice?
- How much does independent legal advice cost?
- Does independent legal advice cover financial advice?
- Who oversees your matter
- What clients say
- Where we act
- Helpful guides
What is independent legal advice, and what is an ILA certificate?
Independent legal advice is legal advice given to one person on their own, by a solicitor who is not acting for anyone else in the same deal. The point is that the advice is only about your interests, so you know what you are agreeing to and can say no.
It is often shortened to ILA. A lender may also ask for an "ILA certificate": a signed confirmation from the solicitor that the advice was given. It is not a guarantee about the deal, and it is not advice on whether the loan is affordable.
When do you need independent legal advice?
Usually when you are taking on a risk for someone else's benefit, or giving something up. Common cases:
- Guarantors. You guarantee a family member's mortgage, so the lender can come to you if they do not pay.
- Living in a home you do not own. The lender wants an adult who lives there, but is not on the title, to agree that its mortgage comes first. This is often called an occupier's consent.
- Joint borrower, sole proprietor. You are named on a mortgage to help someone borrow, but the home will be in their name only.
- Transfer of equity. You are coming off the title, or taking on a bigger share of the mortgage. See our transfer of equity solicitors page.
- Giving up your rights. You agree to a declaration of trust that gives you a smaller share than you might otherwise claim. See our declaration of trust page.
- The lender says so. Some lenders ask for ILA in other cases, and the mortgage offer or the lender's instructions will say.
A gifted deposit usually needs a signed gift letter, not ILA. If the giver will live in the home, the lender may ask them to sign an occupier's consent. Our "Gifted Deposit Check" (£150 + VAT, or "Gifted Deposit Check (from outside the UK)" at £300 + VAT) covers checking where the gift comes from. Our guide to gifted deposits explains it.
Why do lenders ask for independent legal advice?
Lenders want to know that someone who signs for another person's benefit understood the document and was not pressured. If that person later shows they were misled or pressured, the lender's security may be at risk.
The House of Lords set out what lenders and solicitors should do in cases where someone guarantees or secures another person's debt in a non-commercial relationship, in Royal Bank of Scotland v Etridge (No 2) [2001] UKHL 44. In short, the lender relies on a solicitor confirming that the risks were explained to the person face to face, without the borrower present.
What happens at an independent legal advice meeting?
- We check your identity.
- We meet you on your own, without the borrower or anyone else from the deal.
- We go through the document: what you are signing, what you could have to pay, including the borrower's existing debt and the size of the new loan, from the information the lender gives us, and what happens if things go wrong, including losing your home.
- We check you understand, that you are signing of your own free will, and that you know you can refuse.
- If you decide to go ahead, you sign the document and we sign the confirmation your lender asks for.
Your lender's instructions set what the meeting must cover and how it must be held. We tell you before we book it.
What should you bring to an independent legal advice meeting?
- Photo ID and proof of address, so we can check who you are.
- The document you are asked to sign, such as the guarantee, the occupier's consent or the transfer deed, if you have it.
- The mortgage offer or the lender's letter that asks for independent legal advice, so we know what the lender needs from us.
- Your questions. Write them down. The meeting is yours, and nothing you tell us is shared with the borrower without your agreement.
Can the same solicitor give independent legal advice?
It depends on the lender. Some accept advice from a different solicitor at the firm acting on the mortgage. Others want the advice to come from a separate firm. The lender's instructions say which.
A solicitor cannot give you independent advice if your interests conflict with those of another client they are acting for in the same matter. If that applies, we tell you and you see another firm.
How much does independent legal advice cost?
| When | Our fee |
|---|---|
| On a remortgage | "Independent legal advice": £100 + VAT (£120 including VAT) per person, if someone living in the property or guaranteeing the mortgage is not on the title. Our remortgage quote lists it. |
| Any other independent legal advice | We confirm our fee in writing before we start. |
Who pays is agreed before we start. See our remortgage solicitors page for the rest of a remortgage, and our fees page for how our charges work. Fees checked against our quote engine on 29 October 2026.
Does independent legal advice cover financial advice?
No. We explain the legal effect of the document and the risks of signing it. We do not advise on whether a loan is affordable or the right product for you: we are not authorised to give financial or mortgage advice. For that, speak to the lender or an independent mortgage broker.
Who oversees your matter
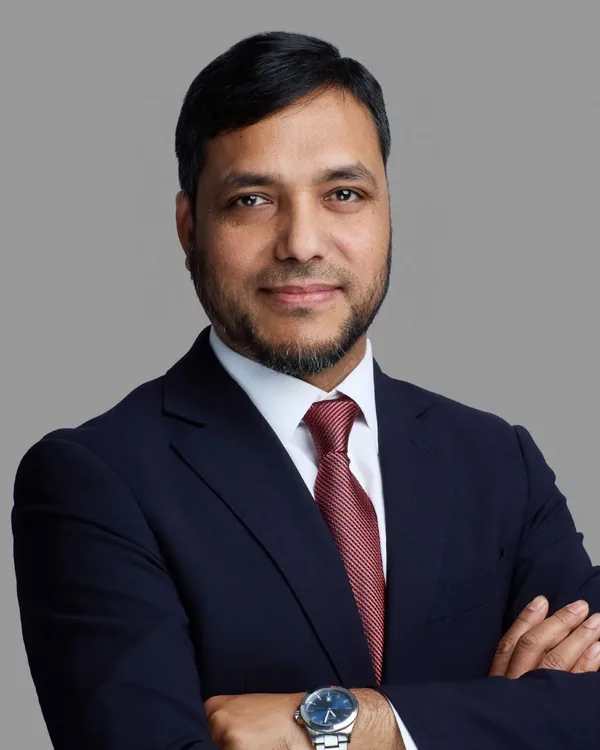
Shah Ali
Senior Partner & Founder
Supervises our conveyancing team.
What clients say
Where we act
-
Leicester office 3rd Floor, St George's House, 6 St George's Way, Leicester LE1 1QZ 0116 393 0334
Conveyancing in Leicester
Waterstone Chambers LLP, trading as Waterstone Legal, is authorised and regulated by the Solicitors Regulation Authority (SRA No. 605949) and CQS accredited.
Helpful guides
This page is general information, not legal, tax or financial advice for your situation. Please speak to us before acting on it.